The 3 golden rules of accounting serve as the foundation for double-entry bookkeeping. In this blog, we’ll dive deep into each rule, provide real-world examples, and discuss practical applications. By the end, you’ll have a clear understanding of how to apply these rules in daily accounting tasks.
Accounting is generally viewed to be a very intricate and demanding subject when it comes to properly applying accounting principles. But beneath every financial transaction lies a simple set of guidelines to bring in accuracy as well as uniformity. And these are called the 3 golden principles of accountancy. If you’re curious, what are the golden rules of accounting? They boil down to three simple principles.
The three principles assist in identifying when to credit or debit an account when it comes to accountancy’s double-entry bookkeeping. The principles are such a vital part of successful financial record-keeping and are important to all users of accountancy, whether a student, business or firm owner, or professional accountant.
Key Takeaways
What are the golden rules of accounting?
- The 3 Golden Rules of Accounting explain how personal, real, and nominal accounts are recorded correctly.
- Double-entry bookkeeping applies debit and credit rules to record each financial transaction accurately.
- Accounting principles help classify accounts and decide what to debit or credit in business transactions.
Comprehensive Summary: 3 Golden Rules of Accounting
- What is Accounting: Accounting is the systematic process of recording, summarising, analysing, and reporting financial transactions.
- Rules of Accounting: Dictate how to record debits and credits for different types of accounts to keep financial records balanced and accurate.
- Golden Rules of Accounting: Core principles in double-entry bookkeeping used to determine whether to debit or credit an account.
- Personal Account Rule: The golden rule for a personal account in accounting is ‘Debit the receiver, credit the giver.’
- Real Account Rule: The golden rule for a real account in traditional accounting is ‘Debit what comes in, and credit what goes out.’
- Nominal Account Rule: The nominal account rule is a core principle in double-entry bookkeeping ‘Debit all expenses and losses, and credit all incomes and gains.’
In this blog post, we will take a step-by-step walk-through of each of the 3 golden rules of accounting with examples, offer real-world examples of how they are used in real-world situations, and discuss how learning these rules will make it easier to ensure accuracy and efficiency in your financial dealings.
Want to Build on Your Accounting Knowledge with a Professional Qualification?
 Speak to Career Specialist
What Are the 3 Golden Rules of Accounting?
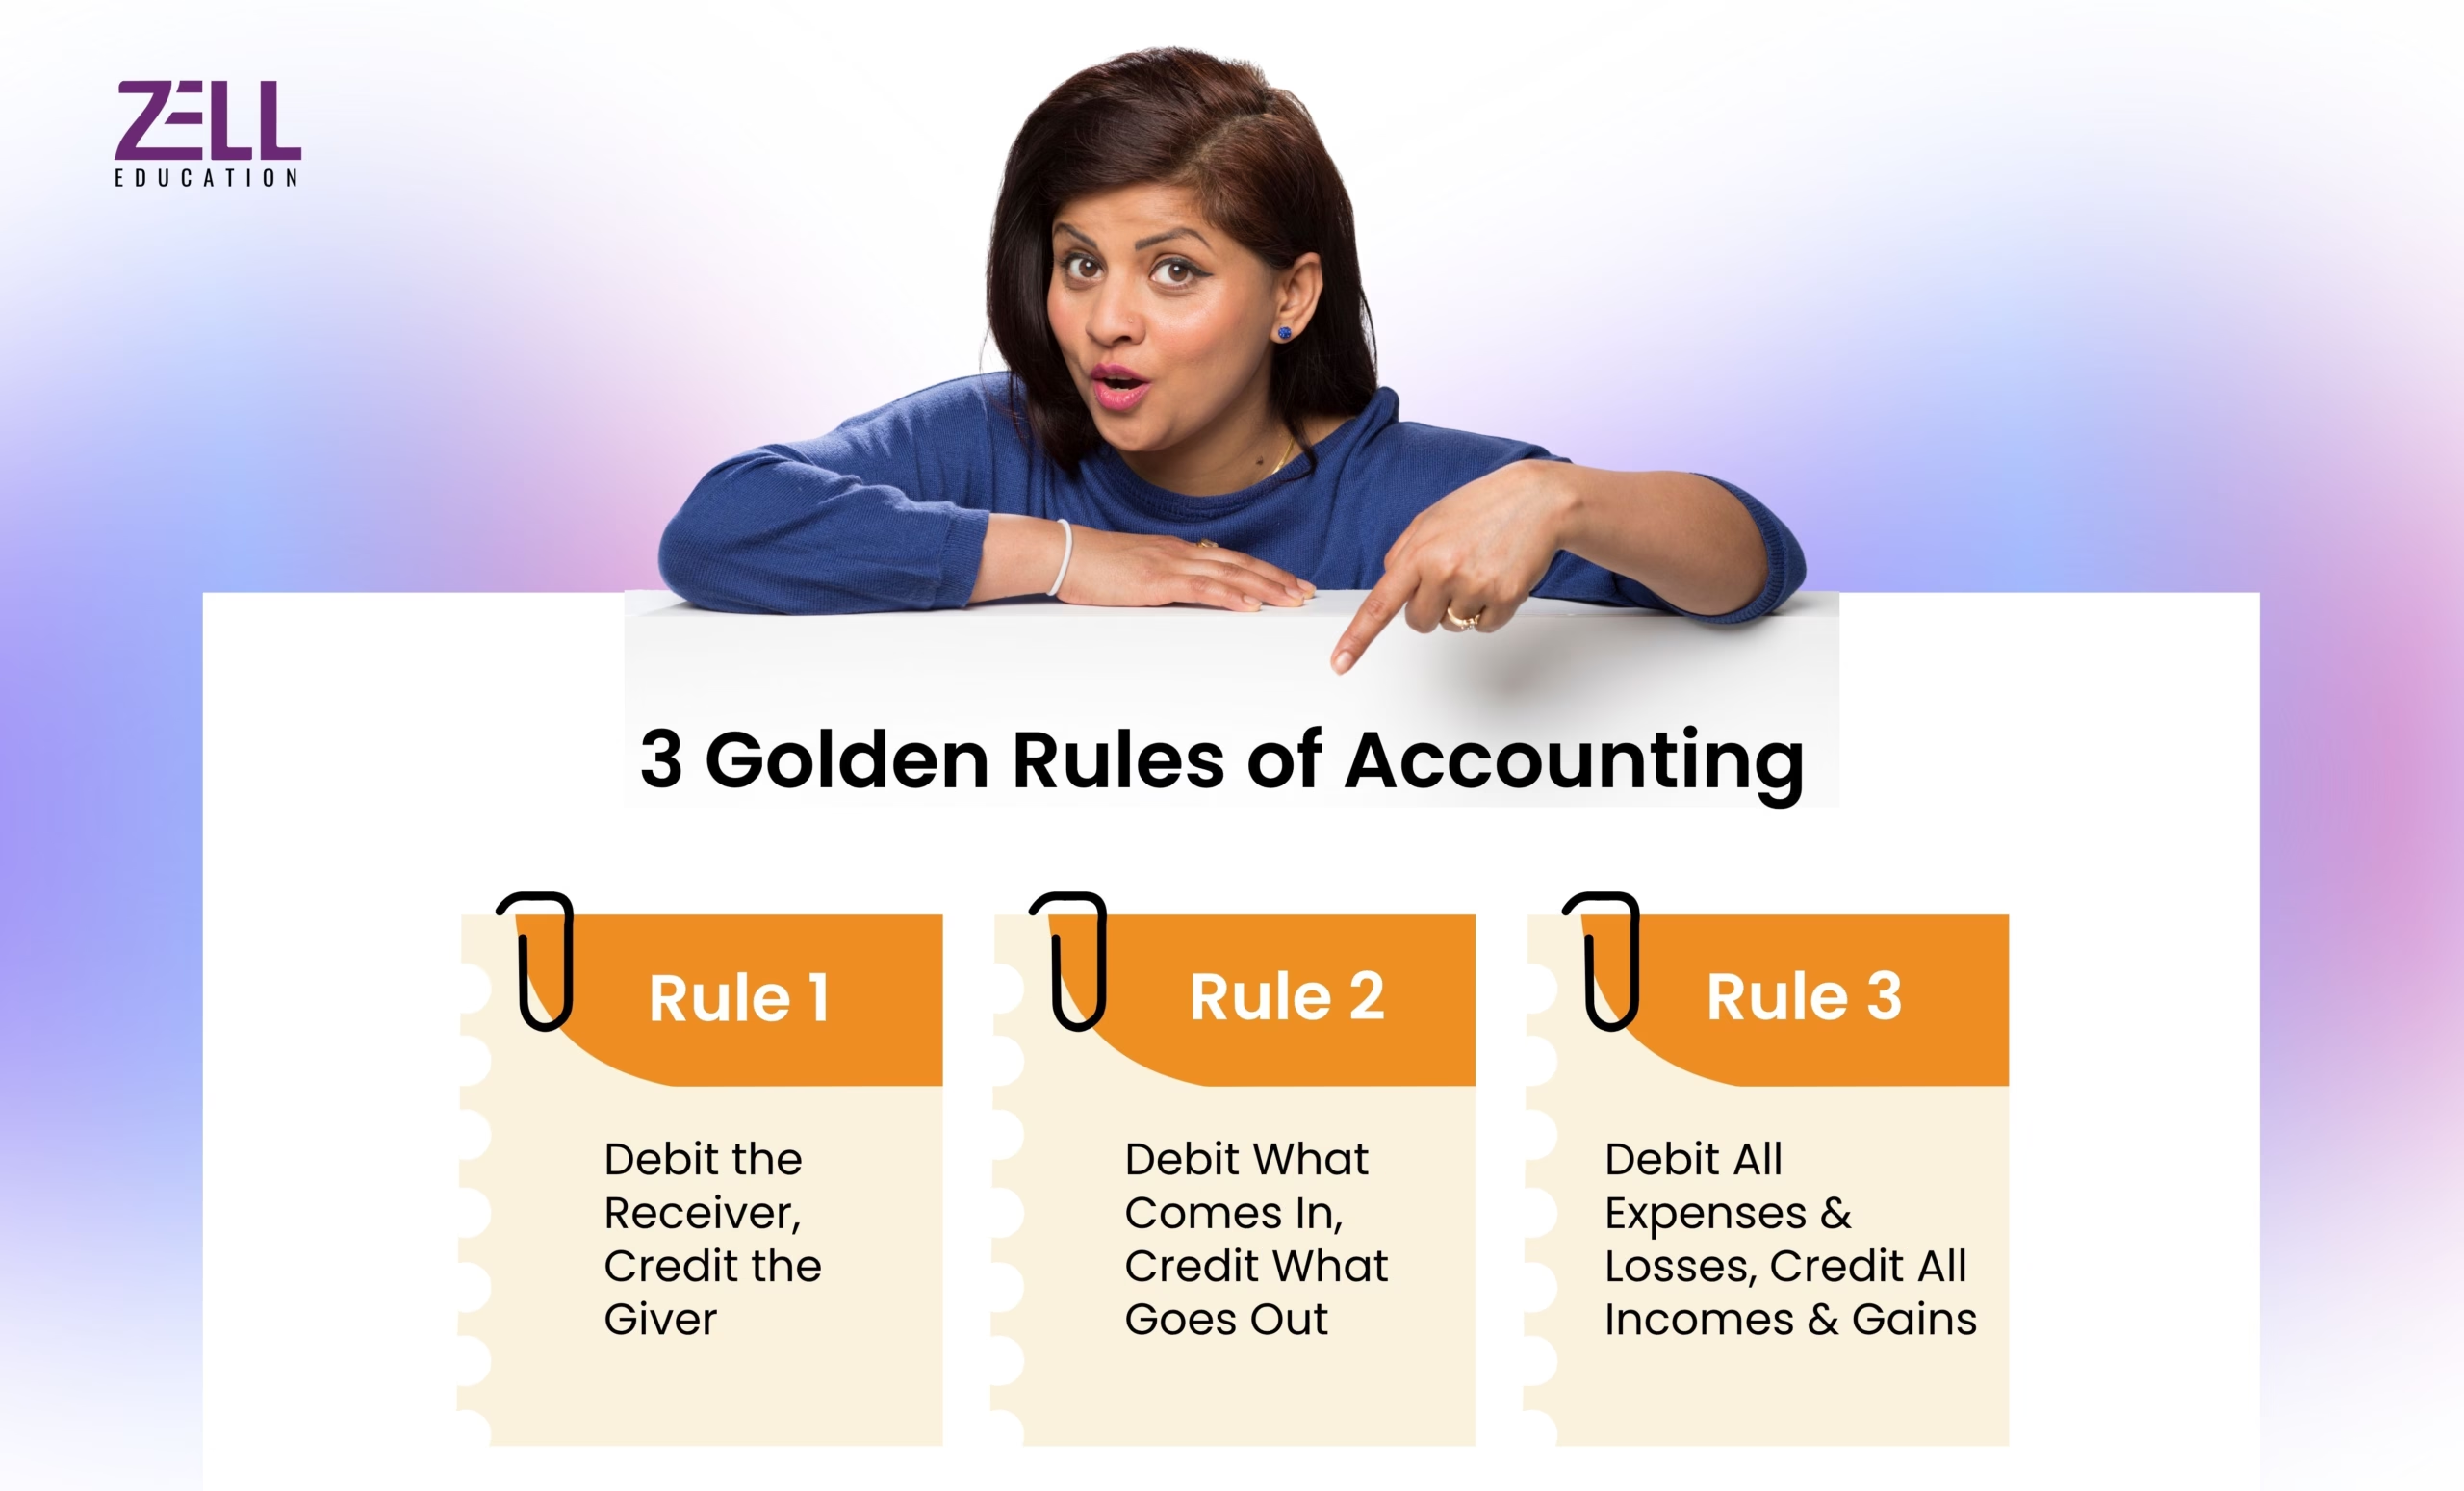
The 3 golden rules of accounting are a fundamental part of the double-entry bookkeeping system. These rules help classify and record transactions in an organised manner, ensuring that every debit has an equal and opposite credit. Here’s an overview of these three important rules:
- Debit the receiver, credit the giver (Personal Account)
- Debit what comes in, credit what goes out (Real Account)
- Debit all expenses and losses, credit all incomes and gains (Nominal Account)
Every rule is attached to a particular type of account: Personal Accounts, Real Accounts, and Nominal Accounts. The rules help accountants keep a balanced ledger and ensure correct financial statements.
Types of Accounts in Accounting
In traditional bookkeeping, the three main types of accounts are Personal Accounts, Real Accounts, and Nominal Accounts. Each type tracks a specific category of business activity and follows its own golden rule for debits and credits.
Personal Accounts
- What it tracks: Transactions with people, firms, companies, or groups.
- Sub-types: Natural persons (individuals), artificial persons (corporations or banks), and representative persons (outstanding or prepaid expenses).
- Examples: Customer accounts, supplier accounts, bank accounts, and capital accounts.
- Golden Rule: Debit the receiver, credit the giver.
Nominal Accounts
- What it tracks: The tangible and intangible assets and properties owned by a business.
- Sub-types: Tangible (physical items) and intangible (non-physical rights or value).
- Examples: Cash, land, buildings, machinery, and patents.
- Golden Rule: Debit what comes in, credit what goes out.
Real Accounts
- What it tracks: Temporary accounts for business revenues, expenses, gains, and losses during an accounting period.
- Sub-types: Expenses/losses and incomes/gains.
- Examples: Rent paid, salaries, sales revenue, and commission earned.
- Golden Rule: Debit all expenses and losses, credit all incomes and gains.
Rule 1: Debit the Receiver, Credit the Giver
(Applied to: Personal Accounts)
Explanation:
This is a rule for Personal Accounts, and what is meant by accounts of individuals, companies, or institutions. When a person receives something, you debit their account, and when they pay something, credit their account. This is a key rule to help keep track of who owes you money and who you owe money to.
Example:
Imagine you pay ₹10,000 to your supplier.
- Debit: Supplier’s account (they receive the money)
- Credit: Cash or Bank (money goes out)
Practical Use:
This rule is applicable in business transactions in ensuring accounts payable and accounts receivable are well accounted for. For instance, when you buy merchandise on account, debit the account of the supplier and credit accounts payable. When paying a debt, debit accounts payable and credit cash or bank.
Proper implementation of this rule is critical in ensuring a good record of customer and vendor debts. Misapplication of this rule results in errors and confusion in accounts payable or accounts receivable books.
Note: This is a major component of the golden rule of personal accounting and can typically be talked about in conjunction with what are the golden rules of accounting when it comes to accounting studies or accountancy.
Rule 2: Debit What Comes In, Credit What Goes Out
(Applied to: Real Accounts)
Explanation:
This is a rule for real accounts, those accounts relating to assets like cash, buildings, machinery, or stock. When an asset enters a business, it’s debited. When an asset is departing, it’s credited.
Example:
You purchase office equipment worth ₹25,000.
- Debit: Equipment (asset coming into the business)
- Credit: Cash or Bank (cash going out)
Practical Use:
The golden account rule is also important for companies with large physical assets. For instance, when purchasing or selling an asset like office equipment or equipment, this rule is responsible for ensuring that this transaction is posted to the right place in your books. This ensures correct records of assets in a company to ensure a well-reflected balance sheet concerning a company’s worth and its financial position.
This same rule is important when dealing with intangible assets like intellectual property or patents. Buying a license to a piece of software would work in the same manner, which is debiting the account for intangible assets and crediting cash.
In manufacturing or retailing contexts, such a provision ensures inventory and equipment are properly accounted for and reported in financial reports.
Note: Understanding what the three golden rules of accounting are is becoming most important for people dealing with physical or intangible assets since it ensures precise record-keeping for company assets and liabilities.
Rule 3: Debit All Expenses and Losses, Credit All Incomes and Gains
(Applied to: Nominal Accounts)
Explanation:
This rule governs nominal accounts, which record all revenues, expenses, and losses. When an expense occurs, it is debited, and when an income or gain is earned, it is credited.
Example:
You pay ₹3,000 for the electricity bill.
- Debit: Electricity Expense (expense incurred)
- Credit: Cash or Bank (money paid out)
You receive interest income of ₹2,000.
- Debit: Bank (money received)
- Credit: Interest Income (income earned)
Practical Use:
The golden rule of nominal accounts guarantees that companies can see their business performance unambiguously. A correct profit and loss account can be prepared by debiting losses and expenses and crediting incomes and gains.
This rule is essential in monitoring outgoings such as rent, utilities, and wages, as well as in recording the revenues from sales, interests, and investments. It is particularly beneficial for businesses to measure their profit margins at the end of a reporting period.
Nominal accounts are shut down at the end of the accounting period, and their balance is transferred to the profit and loss account.
Which Finance Certification Can Take Your Accounting Knowledge Further?
 Explore Finance Certification
3 Golden Rules of Accounting at a Glance
The three golden rules of accounting govern how financial transactions are recorded in a double-entry bookkeeping system. They are structured around three distinct account types: Personal, Real, and Nominal accounts.
| Account Type | Rule | What to Debit | What to Credit | Example |
| Personal Account | Debit the receiver, credit the giver | Receiver | Giver | Paid ₹5,000 to Rahul: Debit Rahul, Credit Cash |
| Real Account | Debit what comes in, credit what goes out | Asset received | Asset given out | Purchased furniture for cash: Debit Furniture, Credit Cash |
| Nominal Account | Debit all expenses and losses, credit all incomes and gains | Expenses/Losses | Incomes/Gains | Paid rent ₹10,000: Debit Rent, Credit Cash |
Examples and Practical Applications
Let us go through a couple more examples of applying the 3 golden rules of accounting to daily business deals.
Example 1: Paid Salary to Employees
- Type: Nominal Account
- Entry:
- Debit: Salary Expense (expense incurred)
- Credit: Cash/Bank (money paid)
Example 2: Purchased Equipment for Office Use
- Type: Real Account
- Entry:
- Debit: Equipment (asset added)
- Credit: Cash/Bank (money paid)
Example 3: Received Loan from Bank
- Type: Personal Account
- Entry:
- Debit: Bank Account (money received)
- Credit: Loan Account (liability owed to bank)
Example 4: Paid Rent in Advance
- Type: Nominal Account
- Entry:
- Debit: Prepaid Rent (asset)
- Credit: Cash (money paid)
These 3 golden rules of accounting with examples highlight how the 3 golden rules of accounting work together to maintain financial order and consistency in a business. By applying the rules accurately, businesses can avoid common mistakes like misclassifying transactions or failing to reconcile accounts.
Common Mistakes and Best Practices
While the 3 golden rules of accounting seem straightforward, beginners often make mistakes when applying them. Below are some common errors and best practices for avoiding them.
Common Mistakes:
- Misidentifying Account Types: The failure to identify an account as personal, real, or nominal may result in incorrect journal postings.
- Double-Entry Errors: Omission in recording either the debit or credit aspect of a transaction results in discrepancies in the books.
- Overlooking Adjustments: Failing to record year-end adjustments for expenditures such as depreciation or accruals can result in distorted financial statements.
- Incorrect Classification of Assets: Mixing tangible and intangible assets might influence how they’re accounted for according to the golden rule of real accounts.
Best Practices:
- Verify Account Type: Prior to recording, always check if it is a personal, real, or nominal account.
- Balance Your Books: Ensure every transaction is recorded with both a debit and a credit to maintain balance.
- Use Accounting Software: Modern software utilised in accounting assists in ensuring compliance with these regulations by reducing human error.
- Double-Check Entries: Periodically check financial statements for discrepancies and correct them when necessary.
Conclusion
To wrap up, the 3 golden rules of accounting are necessary to ensure financial accuracy. These principles form the core of the double-entry bookkeeping technique to ensure transactions are properly classified and recorded.
- Debit the receiver and credit the giver for personal accounts.
- Debit what comes in, and credit what goes out for real accounts.
- Debit all expenses and losses, and credit all incomes and gains for nominal accounts.
Charge all losses and expenditures to nominal accounts and account for all incomes and gains. Mastering these principles ensures precise financial reporting and overall efficiency in account management.
Adhering to the 3 golden rules of accounting with examples not only helps prevent common errors but also maintains accurate books and lays a strong foundation for business success. Earning an ACCA certification further deepens your understanding of these core principles, setting you up for a successful career in accounting and finance.
FAQs on 3 Golden Rules of Accounting
What are the three Golden Rules of Accounting?
They govern debits and credits: Debit the Receiver, Credit the Giver; Debit What Comes In, Credit What Goes Out; Debit All Expenses, Credit All Incomes.
What are the three types of accounts in accounting?
In traditional bookkeeping, the three main types of accounts are Personal Accounts, Real Accounts, and Nominal Accounts
Who actually created the Golden Rules of Accounting?
These rules are derived from the double-entry system formalised by the Franciscan friar, Luca Pacioli, in 1494.
How do these Golden Rules apply to Tally or software?
They are the fundamental logic behind every single entry you make, whether in a register or in modern accounting software.
Why are the Golden Rules separated into different account types?
The rules are categorised by account types (Personal, Real, Nominal) to simplify the recording of diverse business transactions accurately.
Do these rules link to International Financial Reporting Standards?
Yes, these fundamental rules are the bedrock principles underlying all double-entry bookkeeping, including IFRS and GAAP.
Are the Golden Rules essential for a finance certification?
Absolutely. Mastering the Golden Rules of Accounting is non-negotiable for all professional certifications like ACCA or CA.
Where can I find quick practice examples for these rules?
Look for interactive quizzes or short case studies online. Zell Education provides focused, rule-based exercises for quick mastery.
How do the 3 golden rules relate to modern accounting software?
The three golden rules guide manual debits and credits, which modern accounting software automates behind the scenes.
How can I easily memorise the three Golden Rules?
Use mnemonic devices or practical examples. Zell Education uses real-world scenarios to embed these rules quickly.

Current Role
Co-Founder & CEO at Zell Education
Education
- ACCA – Association of Chartered Certified Accountants, Finance (2011 – 2014)
- Bachelor of Commerce (BCom), Financial Markets from H.R. College Of Commerce & Economics (2010 – 2013)
Location
Mumbai, India
Expertise
ACCA Certified
Why Zell?
- • Largest Provider for Global F&A Courses
- • 4.6 Google Review Rating
- • 1000+ Students placed Annually
- • 500+ Active Hiring Partners
- • Placement Opportunities at the Big 4
- • 100+ Global & Indian Rank Holders
- • 100+ Faculty Network
Speak to A Career Counselor
Zell's 10th Anniversary Offer - Avail a 10% Scholarship